What is the scope and industry significance of the Combat Sports Products Market?
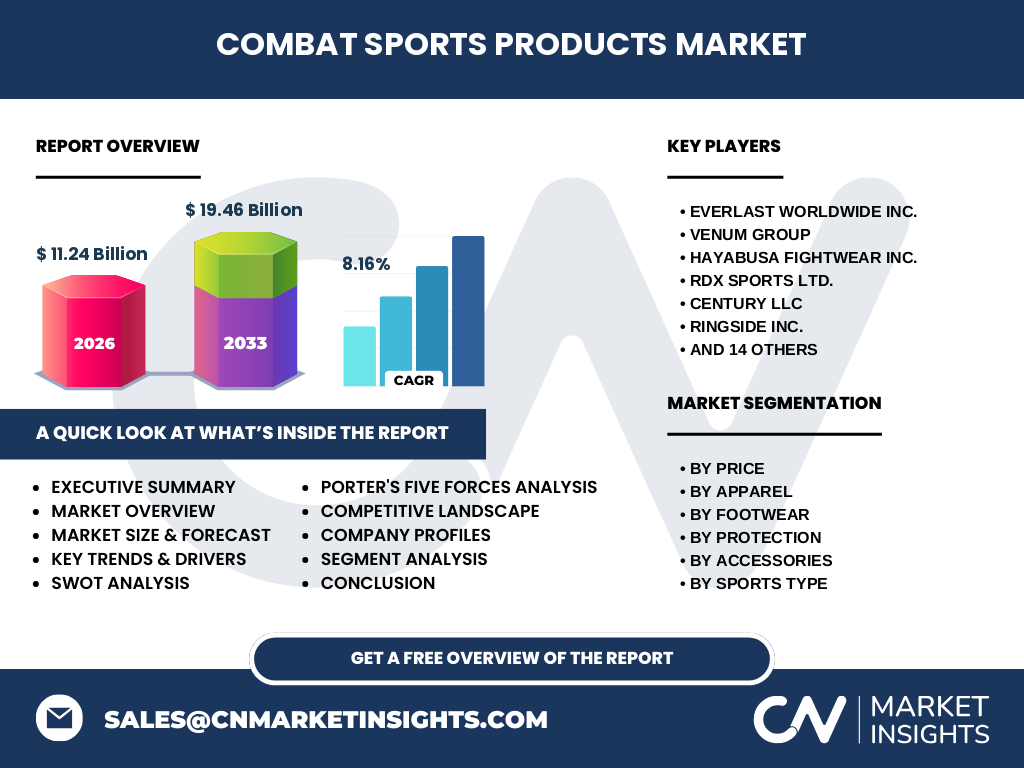
Our analysis indicates that the Combat Sports Products Market encompasses specialized equipment, apparel, footwear, and accessories tailored for disciplines like boxing, mixed martial arts, and wrestling. The market is valued at $11.24 Billion in 2026, underscoring its vital role in supporting professional athletes and fitness enthusiasts globally through high-performance protective gear and specialized training apparatus.
Key market drivers, restraints, challenges, and opportunities shaping the sector
Growth is propelled by rising disposable incomes and surging popularity of combat sports fitness classes. However, supply chain bottlenecks for raw materials like genuine leather and high-density foam act as primary restraints. Opportunities abound in e-commerce expansion and eco-friendly manufacturing innovations led by pioneers like Venum Group and Everlast Worldwide Inc.
Emerging trends and growth patterns in the industry
The shift toward smart-connected punching bags and biometric-integrated hand protection is revolutionizing training regimens. Consumers increasingly demand antimicrobial compression wear and sustainable Gi (Karate, Judo) fabrics, prompting brands to overhaul traditional manufacturing lines to capture high-margin segments.
COVID-19 impact analysis and pandemic recovery trajectory
Lockdowns temporarily closed combat sports gyms, stalling offline retail sales. Yet, the crisis catalyzed a home-fitness boom, driving unprecedented demand for accessories like jump ropes and heavy bags. The recovery trajectory has been exceptionally robust, fueled by the reopening of sanctioned training facilities and a resurgence in live combat sports events.
Competitive Benchmarking: Major players and strategic market dynamics
The competitive landscape features a mix of legacy equipment providers and agile modern brands. Key market participants like Hayabusa Fightwear Inc. and RDX Sports Ltd. leverage advanced ergonomic R&D to secure market share, while industry stalwarts such as Century LLC maintain dominance through extensive global wholesale distribution networks.
Executive Summary: High-level synthesis of key market findings
This comprehensive overview reveals a thriving sector driven by mainstream fitness integration and digital consumer engagement. The data highlights a robust projected expansion, reaching $19.46 Billion by 2033 at a notable 8.16% CAGR from 2027, making this market a prime target for strategic capital allocation and brand expansion.
Combat Sports Products Market forecast from 2027 to 2033
Driven by rising participation rates across non-professional consumer groups, our research forecasts the market to expand from its baseline valuation to $19.46 Billion by 2033. Achieving an 8.16% CAGR between 2027 and 2033, the sector will experience accelerated growth led by surging demand in developing Asian and Latin American economies.
Segmentation analysis across price, apparel, footwear, protection, and accessories
The market segments into low, medium, and high price tiers. Core categories include apparel (rash guards, fight shorts, compression wear), specialized footwear (boxing and wrestling shoes), protection (headgear, body protectors, hand protection), and training accessories like focus mitts and shields, serving both professional and non-professional tiers.
Geographic distribution and performance across regional markets
Regional performance varies significantly, with North America leading in revenue generation due to high concentrations of martial arts academies and major promotional events. Meanwhile, Asia-Pacific exhibits the fastest growth velocity, underpinned by deep-rooted historical traditions in karate, judo, and kickboxing across Japan, Thailand, and South Korea.
In-depth regional review of high-growth territories
North America benefits from mature distribution networks through major ports and widespread digital adoption. Conversely, the European market prioritizes strict safety certifications mandated by regional combat sports commissions, favoring high-end protective gear from specialized regional innovators and international distributors alike.
Strategic positioning of leading companies in the industry
Industry leaders carve out distinct niches to maintain competitive edges. Brands like Rival Boxing Gear Inc. and Title Boxing LLC focus on premium boxing innovations, whereas Fuji Sports Inc. and Tatami Fightwear Ltd dominate grappling and martial arts apparel with specialized, durable fabrics tailored for intense ground combat.
Porter's Five Forces analysis of the competitive environment
The threat of new entrants remains moderate due to high brand loyalty and safety certification hurdles. Bargaining power of buyers is high given numerous online alternatives, while supplier power is tempered by diverse raw material sourcing options available to major manufacturing conglomerates.
SWOT analysis highlighting internal and external strategic factors
Strengths include robust brand heritage among legacy firms, while weaknesses involve vulnerability to volatile raw material costs. Opportunities lie in emerging digital fitness subscriptions; threats include potential regulatory crackdowns on concussion risks in combat sports that could temporarily depress headgear and protection sales.
Value chain analysis from raw material sourcing to end-user delivery
The value chain begins with the procurement of synthetic leather, high-density EVA foam, and moisture-wicking textiles. Manufacturing occurs primarily in specialized hubs across Asia, followed by complex logistics operations through major maritime ports, and ultimate distribution via online platforms and brick-and-mortar specialty sporting goods stores.
Investment insights and high-potential areas for strategic allocation
Investors should target high-growth product segments such as advanced hand protection and smart training accessories. Companies integrating sustainability into their supply chains or leveraging direct-to-consumer e-commerce channels present superior risk-adjusted return profiles throughout the forecast period.
Conclusion and key takeaways for stakeholders
The Combat Sports Products Market industry trends indicate a shift toward premium, technology-enabled gear. With the market projected to hit $19.46 Billion by 2033, stakeholders must invest in localized digital marketing, advanced material science, and omnichannel retail strategies to capture expanding consumer demand.
Research methodology and baseline estimation techniques
Baseline estimates are meticulously triangulated by combining proprietary trade registry data, primary stakeholder interviews with executives from Gameness Sports and Combat Corner Professional LLC, and secondary macroeconomic indicators regarding disposable income and gym memberships across key geographic zones.
Scope of the report and analytical coverage parameters
This report covers global market dynamics from 2026 to 2033, evaluating quantitative data across all major product types, sports disciplines, and distribution channels. Limitations include exclusion of unlicensed counterfeit goods and informal local manufacturing operations lacking official trade documentation.
Recent developments, corporate announcements, and strategic partnerships
Recent market activity highlights aggressive expansion strategies, including Meister International LLC and Anthem Athletics LLC launching direct-to-consumer digital platforms. Meanwhile, collaborations between equipment innovators and professional fighting promotions have accelerated product visibility and consumer adoption worldwide.